A company reports higher earnings. Revenue is growing, margins look healthy, and net income reaches a new high. Then you open the cash flow statement and find something unexpected: free cash flow has fallen sharply.
Is that a warning sign?
Not necessarily.
Free cash flow vs earnings is one of the most useful financial statement comparisons investors can learn to interpret. Earnings measure accounting profitability, while cash flow shows how cash actually moves through the business. Because they measure different things, they can move in opposite directions even when neither number is wrong.
The important question is not simply which number is higher. It is where the gap appears and what caused it.
Quick Answer: Find Where the Cash-Flow Gap Begins
Understanding free cash flow vs earnings starts with identifying whether the divergence occurs between net income and operating cash flow or between operating cash flow and free cash flow.
A gap between earnings and operating cash flow can point toward working-capital movements, non-cash adjustments, or weak cash conversion. A gap that appears mainly after operating cash flow often points toward higher capital expenditures.
A useful way to trace the numbers is:
Earnings → Operating Cash Flow → CAPEX → Free Cash Flow
Find where the divergence begins before deciding what it means.
Start With the Bridge From Earnings to Cash
Net income is calculated under accrual accounting. Revenue and expenses can therefore be recognized in a different period from the related cash receipt or payment.
Operating cash flow helps bridge that difference by adjusting net income for non-cash items and changes in operating assets and liabilities.
Free cash flow goes another step by considering capital spending.
A common simplified calculation is:
Free Cash Flow = Operating Cash Flow − Capital Expenditures
Free cash flow is not a standardized GAAP line item, so investors should check exactly how a company defines the measure when management reports it.
Consider a hypothetical company:
| Metric | Year 1 | Year 2 |
|---|---|---|
| Net income | $100 million | $130 million |
| Operating cash flow | $140 million | $120 million |
| Capital expenditures | $40 million | $70 million |
| Free cash flow | $100 million | $50 million |
Net income increased 30%, but free cash flow fell 50%.
The numbers show the divergence. They do not yet explain it.
To do that, investors need to identify which part of the cash-flow bridge changed.
The Two Places the Earnings–FCF Gap Can Appear
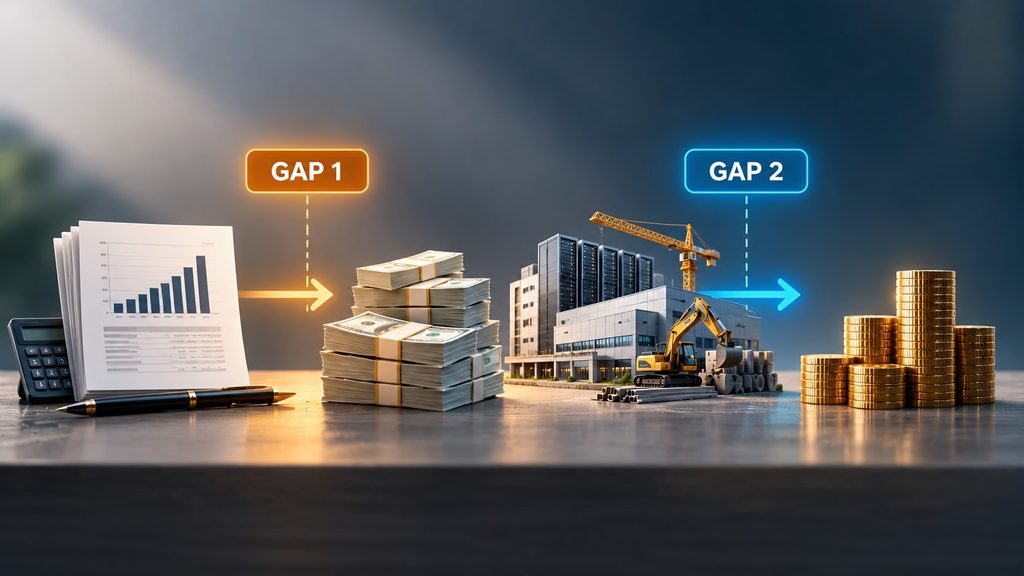
Instead of treating every decline in free cash flow the same way, divide the analysis into two gaps.
Gap 1: Earnings → Operating Cash Flow
The first step is determining whether reported profit is converting into operating cash.
Accounts receivable, inventory, accounts payable, other working-capital movements, and non-cash expenses can all create differences between net income and operating cash flow.
Suppose a company reports 10% revenue growth while accounts receivable increases 35%.
That does not prove the company has a problem. Customers may have purchased more near the end of the reporting period, payment terms may have changed, or normal timing could explain the difference.
But if receivables repeatedly grow much faster than revenue while operating cash flow weakens, investors have a reason to examine cash conversion more closely.
Inventory can have a similar effect. A company may spend cash building inventory before those products are sold, reducing operating cash flow even while reported earnings remain healthy.
What matters is whether changes in receivables and inventory make sense relative to sales, operating conditions, and subsequent results.
Persistent divergence between earnings and operating cash flow can ultimately become an earnings-quality question: how much of the reported profit is translating into cash generated by the underlying business?
Gap 2: Operating Cash Flow → Free Cash Flow
The second gap occurs after the business has generated operating cash.
Capital expenditures, or CAPEX, can significantly reduce free cash flow even when operating cash generation is improving.
Suppose a manufacturer spends $200 million building a new factory.
The cash leaves the business now, but the entire $200 million generally does not become an income-statement expense immediately. A qualifying long-lived asset is generally recorded on the balance sheet, with its cost recognized over time through depreciation.
A company investing heavily in factories, stores, equipment, or data centers can therefore report rising earnings and operating cash flow while free cash flow falls.
Investors then need to evaluate what the company is receiving in exchange for that spending.
Expansion CAPEX that eventually produces profitable growth may support long-term value creation. Heavy investment that generates inadequate returns can do the opposite.
The cash flow statement tells you where the money went. Evaluating the return on that investment requires another step.
Real-World Case: Amazon’s Earnings Rose While Free Cash Flow Fell
Amazon’s 2025 results provide a useful real-world example of how free cash flow vs earnings can diverge during a period of heavy investment.
According to Amazon’s 2025 Form 10-K, net income increased from approximately $59.25 billion in 2024 to $77.67 billion in 2025.
Operating cash flow also increased, from approximately $115.88 billion to $139.51 billion.
Yet Amazon’s reported free cash flow moved sharply in the opposite direction.
| Amazon | 2024 | 2025 | Approx. Change |
|---|---|---|---|
| Net income | $59.25B | $77.67B | +31% |
| Operating cash flow | $115.88B | $139.51B | +20% |
| Property/equipment purchases, net of sales and incentives | $77.66B | $128.32B | +65% |
| Reported free cash flow | $38.22B | $11.19B | -71% |
Figures are rounded from Amazon’s 2025 Form 10-K.
The key point is that Amazon’s 2025 divergence appeared primarily between operating cash flow and free cash flow, not between earnings and operating cash flow.
Operating cash generation increased, while purchases of property and equipment, net of proceeds from sales and incentives, rose substantially.
That additional investment spending pushed reported free cash flow much lower.
Rather than assuming that lower FCF reflects deteriorating operations, investors can examine whether the additional capital investment eventually generates enough revenue, operating profit, and cash flow to justify the money committed.
Higher CAPEX does not prove that an investment program will succeed. Future financial results still need to confirm the economic return.
Non-Cash Expenses Add Another Layer
The earnings-to-cash relationship can also move in the opposite direction.
Depreciation is a common example.
A company that purchased equipment in an earlier period may recognize depreciation expense today without making an equivalent cash payment today. Under the indirect cash flow method, depreciation and other non-cash items are among the adjustments used to reconcile net income to operating cash flow.
Stock-based compensation can create another difference.
But “non-cash” does not mean “economically irrelevant.”
Depreciation may reflect the consumption of assets that eventually require replacement. Stock-based compensation may dilute existing shareholders even though it does not require the same immediate cash outlay as a cash salary.
This is why earnings and cash flow are better viewed as complementary measures rather than competing versions of the same number.
When Does Falling Free Cash Flow Become a Warning Sign?
Falling free cash flow deserves closer attention when the weakness persists across multiple periods and appears alongside other problems.
Potential warning signs include:
- receivables consistently growing faster than revenue;
- repeated inventory buildup without corresponding sales growth;
- deteriorating operating cash flow despite rising earnings;
- increasing debt or reliance on outside financing;
- heavy capital spending without evidence of stronger future operating performance; and
- management explanations that are not supported by subsequent financial results.
No single signal proves that a business is deteriorating.
The concern becomes more meaningful when several problems persist together or the expected reversal never appears.
A Five-Step Framework for Analyzing Free Cash Flow vs Earnings
When earnings rise but free cash flow falls, use the financial statements in a specific order.
Step 1: Compare Multiple Periods
Start with the trend rather than one quarter or year.
Determine whether the divergence is temporary, recurring, or widening.
One unusual period may reflect timing. A persistent multi-year gap usually requires a stronger explanation.
Step 2: Find the First Gap
Compare net income with operating cash flow.
If earnings are rising but operating cash flow is weakening, examine receivables, inventory, payables, non-cash adjustments, and other working-capital movements.
The goal is to determine how effectively reported earnings are converting into operating cash.
Step 3: Find the Second Gap
Next, compare operating cash flow with free cash flow.
If operating cash generation remains healthy but FCF falls sharply, examine capital expenditures.
Look at what management is building, why spending has increased, and what future financial results would justify that investment.
Step 4: Separate Temporary Effects From Structural Problems
Some cash-flow differences can reverse naturally.
Inventory can be sold. Receivables can be collected. A large construction program can eventually move beyond its peak spending period.
Structural problems are different. Persistently weak collections, repeated inventory accumulation, or rising capital requirements without adequate returns deserve closer examination.
Step 5: Test the Explanation Against Future Results
Management’s explanation is a starting point, not the end of the analysis.
If management says inventory growth is temporary, later inventory and sales figures can test that explanation.
If higher CAPEX is expected to support growth, future revenue, margins, utilization, and cash generation can show whether that capital is producing economic returns.
A credible explanation should eventually connect to observable results.
Which Matters More: Free Cash Flow or Earnings?
When comparing free cash flow vs earnings, neither metric should be analyzed in isolation.
Earnings measure accounting profitability, while operating cash flow and free cash flow reveal different stages of cash generation and reinvestment.
The relationship between them is often more informative than choosing one as the “better” metric.
The Practical Takeaway
The most useful question in free cash flow vs earnings analysis is not:
“Which metric is better?”
It is:
“Where exactly does the gap appear, and what caused it?”
Follow the sequence:
Earnings → Operating Cash Flow → CAPEX → Free Cash Flow
If the first gap is the problem, investigate cash conversion, working capital, and earnings quality.
If the second gap is the problem, investigate CAPEX, reinvestment, and the future return on that capital.
Amazon’s 2025 results show why the distinction matters. Its operating cash flow increased while free cash flow declined sharply as property and equipment spending increased substantially.
That does not settle whether the spending will ultimately create value. It tells investors which issue to investigate next.
The real value of comparing free cash flow with earnings is not choosing one metric over another, but using the gap between them to understand what is actually happening inside the business.
This article is for educational purposes only and does not constitute individualized investment, financial, or tax advice.
📚 Related Articles
Free Cash Flow Explained: Why Profitable Companies Can Still Run Into Trouble
Why Profitable Companies Run Out of Cash: 5 Causes Investors Should Know
How to Read Financial Statements: A Simple and Powerful Beginner’s Guide
High Interest Rates and the Economy: Why Can Growth Stay Strong?
If high interest rates are supposed to slow the economy, why can consumers keep spending,…
Can AI Become a Monopoly? Where the Real Economic Moats Are
Artificial intelligence appears to have many ingredients that could produce powerful monopolies. Training frontier models…
Can Big Tech Maintain Its Profit Margins in the AI Era?
Artificial intelligence is creating new revenue opportunities for Big Tech, but it is also changing…