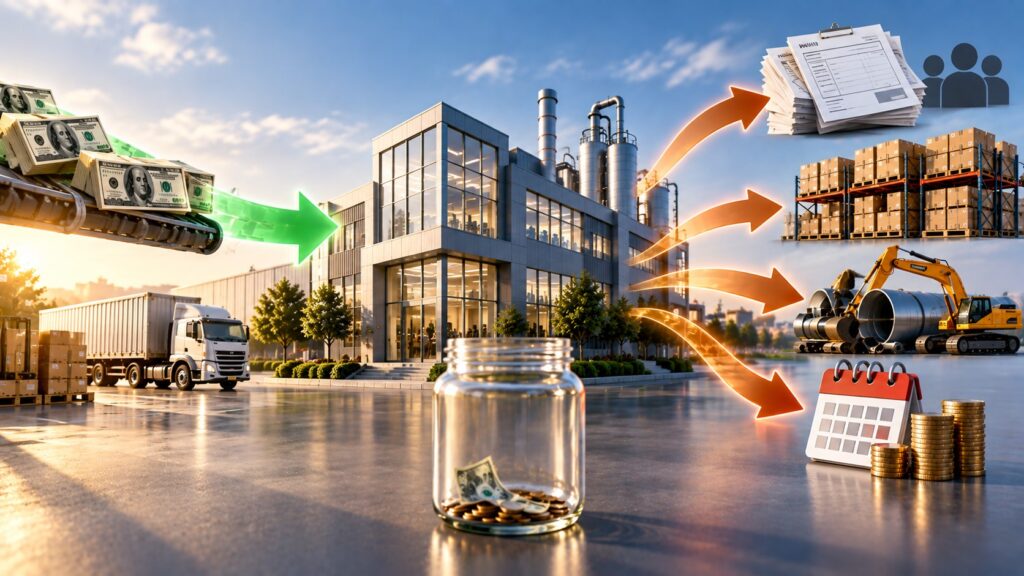
Quick Answer: Profitable companies run out of cash when money leaves the business faster than it arrives, even while the income statement shows positive earnings. Five common causes are slow customer payments, inventory buildup, rapid growth, heavy capital expenditures, and debt or other obligations coming due. Investors can diagnose the problem by comparing net income with operating cash flow and tracing where the cash is being absorbed.
Profitability, cash generation, and liquidity measure different things. A company can report healthy earnings while cash is tied up in receivables or inventory, invested in long-term assets, or needed for upcoming payments.
For investors, the key question is not simply, “Is this company profitable?”
It is:
Can the business turn its reported profits into enough cash to meet its obligations?
Answering that question requires connecting the income statement, balance sheet, and cash flow statement rather than relying on net income alone.
Why Profitable Companies Run Out of Cash Despite Positive Earnings
Under accrual accounting, revenue and expenses are generally recognized when economic activity occurs, not necessarily when cash changes hands.
Consider a hypothetical manufacturer that sells $1 million of equipment in December and gives customers 90 days to pay.
The company may recognize the revenue in December even though much of the cash will not arrive until the following quarter. If those sales contribute to $150,000 of net income, the income statement can show a profit while the company still needs cash today for payroll, suppliers, interest, and other expenses.
The U.S. Securities and Exchange Commission (SEC), in its guide to financial statements, explains that an income statement reports earnings over a period, while a cash flow statement shows cash flowing into and out of the company. For most companies, the operating section also reconciles net income with the cash generated or used by operations.
That reconciliation is often where a cash squeeze becomes visible.
1. Accounts Receivable Can Delay Cash Collection
One reason profitable companies run out of cash is that a recorded sale does not necessarily mean the cash has been collected.
Suppose a business reports $10 million in revenue and $1 million in net income, but accounts receivable increases by $2 million because customers have not yet paid for a significant portion of those sales.
The company has recognized revenue without collecting all the corresponding cash.
That does not automatically signal a problem. Seasonality, business growth, and different payment terms can all affect receivables.
The useful comparison is whether receivables are behaving reasonably relative to sales.
If receivables repeatedly grow much faster than revenue, investors have a reason to investigate collection timing and revenue quality more closely.
2. Inventory Can Absorb Cash Before Products Are Sold
Inventory creates a different timing problem.
A retailer or manufacturer may need to purchase materials or products before receiving cash from customers.
Consider this simplified hypothetical example:
| Metric | Year 1 | Year 2 |
|---|---|---|
| Revenue | $10.0M | $12.0M |
| Net income | $0.8M | $0.9M |
| Inventory | $1.5M | $3.5M |
| Receivables | $1.0M | $1.8M |
Revenue increased 20%, and net income also improved. But inventory increased by $2 million while receivables increased by another $800,000.
Those movements can absorb cash even while reported earnings are rising.
The investor’s question should therefore be:
Is additional working capital supporting productive growth, or is cash becoming trapped in inventory and unpaid invoices?
The direction of working capital alone does not answer that question. Investors need to understand why those accounts changed.
3. Fast Growth Can Increase the Need for Cash
Growth itself can create a cash requirement.
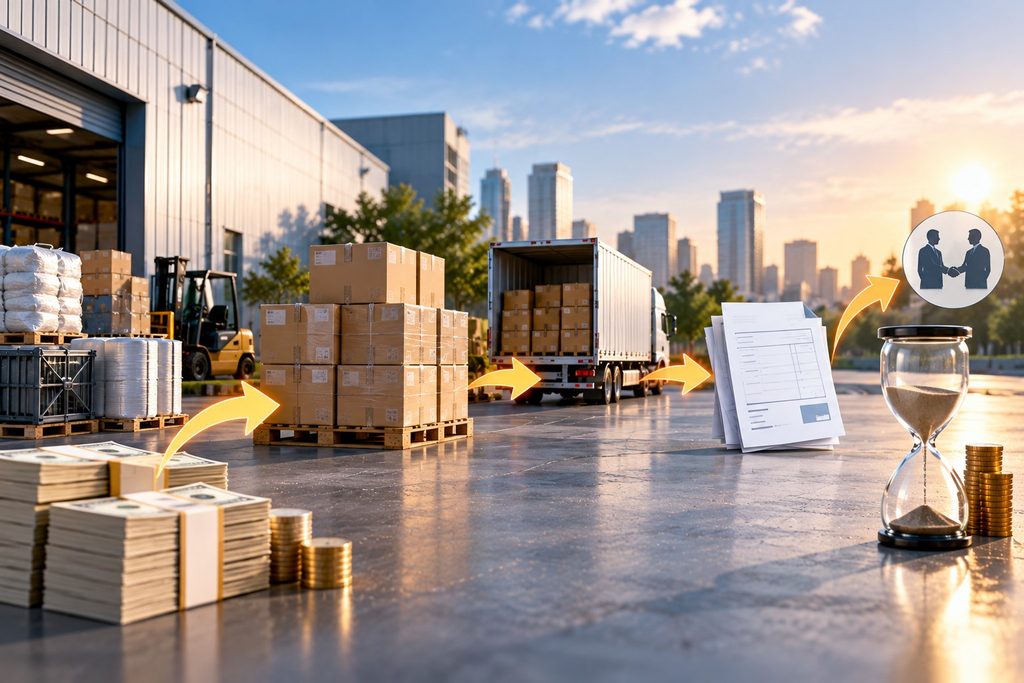
Imagine a company that must buy inventory, pay suppliers, deliver the product, and then wait 60 days for the customer to pay.
Each new order can require additional cash before the associated revenue turns into cash.
If sales grow rapidly, the company may need to finance substantially more inventory and receivables. Earnings can rise while the business becomes more dependent on existing cash or external financing.
This creates a counterintuitive result:
Profitable companies can run out of cash during rapid growth because expansion may require cash before it produces cash.
For investors, revenue growth is therefore only part of the picture. The next question is how much additional working capital the business needs to support that growth.
4. Capital Expenditures Can Create a Large Cash Drain
Working capital is not the only reason profitable companies run out of cash.
A profitable business may spend heavily on factories, machinery, data centers, stores, vehicles, or other long-term assets. These investments are generally called capital expenditures, or Capex.
Suppose a hypothetical company purchases a $5 million machine that will be used for several years.
The cash required for the purchase leaves the business, but the entire $5 million generally does not become an income-statement expense immediately. Instead, the asset’s cost is typically allocated across its useful life through depreciation.
Accounting profit can therefore remain positive while significant cash is being invested.
This is one reason investors often compare operating cash flow with capital expenditures instead of stopping at net income.
But high Capex is not automatically negative. A company building productive new capacity is economically different from one spending heavily simply to maintain aging assets.
The important questions are how much cash is being spent and what that spending is intended to accomplish.
5. Debt and Other Obligations Can Create a Liquidity Squeeze
Another reason profitable companies run out of cash is that major obligations can come due before cash generation is sufficient to cover them.
These can include debt principal, interest, leases, supplier payments, taxes, and other contractual commitments.
Suppose one profitable company has temporarily weak operating cash flow but substantial cash reserves and little debt due soon. Another company has similar earnings and cash generation but faces a major debt maturity in six months.
Their liquidity positions are not equivalent.
Liquidity is partly a timing problem: cash must be available when obligations come due.
A business can own valuable factories, equipment, or inventory and still face pressure if those assets cannot be converted into usable cash quickly enough.
Same Profit, Very Different Cash Position
Consider two hypothetical companies that each report $10 million in net income:
| Cash Measure | Company A | Company B |
|---|---|---|
| Operating cash flow | $14M | $3M |
| Capital expenditures | $4M | $8M |
| OCF minus Capex | $10M | −$5M |
Their accounting profits are identical, but their cash positions are very different. This helps explain why profitable companies run out of cash even when reported earnings remain positive.
Company B has a $5 million deficit under this simplified calculation. It must cover that gap through some combination of existing cash, borrowing, new shares, asset sales, reduced investment, or improved working capital.
This OCF-minus-Capex calculation is deliberately simplified and is not a complete valuation method. Definitions of free cash flow can also vary.
Its purpose is narrower: identical accounting profits can conceal very different funding needs.
Once investors see that gap, the next task is to determine what caused it.
The Profit-to-Cash Check: A 5-Step Framework
The five causes above explain how a cash squeeze can develop. The Profit-to-Cash Check turns those causes into a practical sequence for investigating a company’s financial statements.
It is a diagnostic framework, not a buy-or-sell signal.
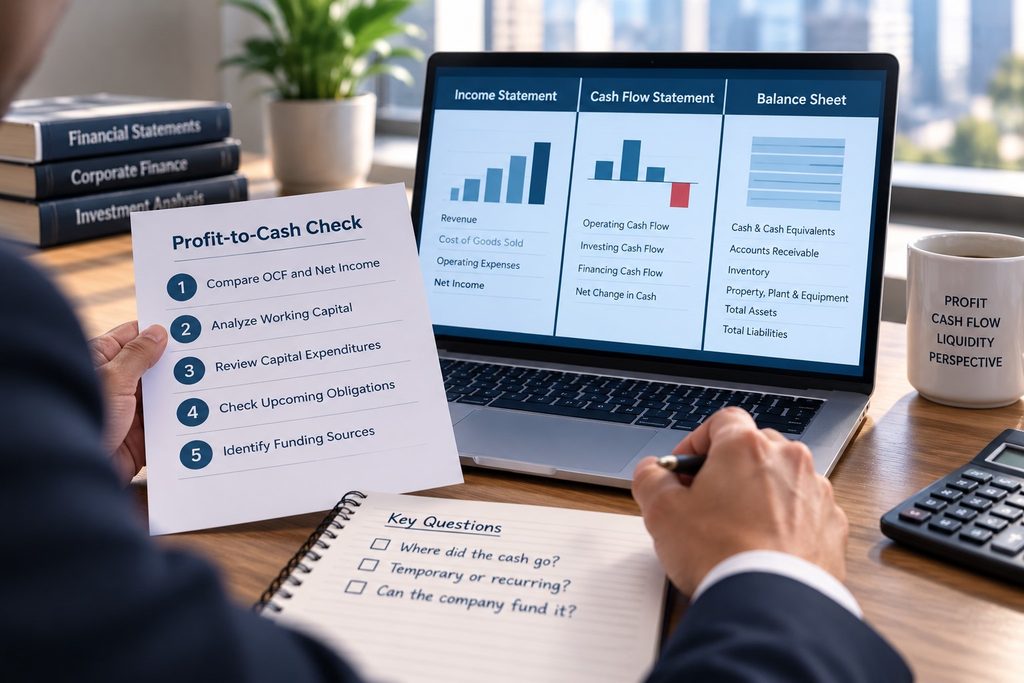
Step 1: Compare Operating Cash Flow With Net Income
Start with net income and cash flow from operating activities.
One quarter of weak cash conversion may reflect seasonality or normal timing differences. A recurring gap deserves more investigation.
If earnings rise while operating cash flow repeatedly lags, examine the reconciliation between the two figures.
The goal is not to find a predetermined “good” ratio. It is to identify what is causing earnings and cash generation to move differently.
Step 2: Find Where the Cash Is Being Absorbed
Next, examine working-capital accounts.
If receivables are rising rapidly, compare their growth with revenue and investigate collection timing or payment terms.
If inventory is increasing, ask whether it supports expected sales or reflects products that are becoming harder to move.
Accounts payable matters too. Changes in when a company pays suppliers can temporarily raise or lower operating cash flow.
The direction of an account alone is less informative than the economic reason behind the change.
Step 3: Measure the Reinvestment Burden
Examine how much cash the company spends on property, equipment, and other long-term assets.
Then consider the business model.
Capital-intensive industries naturally require more reinvestment than asset-light businesses. Capex can also rise temporarily during a major expansion.
The useful question is whether operating cash generation can reasonably support the company’s required reinvestment over time.
Step 4: Check What Must Be Paid Soon
Move to the balance sheet and liquidity disclosures.
Look for cash and cash equivalents, short-term borrowings, current debt maturities, interest requirements, and other material commitments.
This changes the analysis from:
“Is cash flow weak?”
to:
“Does the company have enough financial flexibility to handle the weakness?”
Those are not the same question.
Step 5: Identify Who Is Funding the Gap
Finally, determine how any cash deficit is being financed.
A company may use existing cash, bank credit, bonds, newly issued shares, or asset sales.
External financing can be reasonable during expansion. But repeated borrowing may increase interest expense and refinancing risk. New share issuance can dilute existing shareholders. Asset sales may not provide a repeatable source of cash.
Temporary Investment or Structural Cash Weakness?
After completing the Profit-to-Cash Check, focus on cause, duration, and financing capacity.
A profitable company constructing a new factory may experience temporarily weak cash flow because of elevated Capex. A different company may repeatedly consume cash because receivables are difficult to collect, inventory continues to accumulate, and borrowing keeps increasing.
Both may initially report positive net income and declining cash.
To distinguish them, ask:
- What is consuming the cash?
- Is the requirement temporary or recurring?
- Is the spending supporting productive economic activity?
- How long can the company finance the gap?
These questions help separate a temporary investment cycle from a potentially more persistent cash-generation problem.
Real-World Example: ADM’s Earnings Rose While Operating Cash Flow Fell
Archer-Daniels-Midland’s Form 10-Q for the six months ended June 30, 2026 provides a useful real-world example.
ADM reported net earnings including non-controlling interests of $1.215 billion, compared with $509 million during the first six months of 2025.
Operating cash flow moved in the opposite direction.
Net cash provided by operating activities declined to $1.3 billion, from $4.0 billion in the comparable 2025 period.
ADM said the decrease in operating cash flow was primarily driven by changes in net working capital, partially offset by higher earnings. The filing identified negative working-capital changes involving inventories, segregated investments, trade receivables, other current assets, and payables to brokerage customers, with positive offsets from accrued expenses and other payables and trade payables.
This is a historical financial-statement example, not an investment judgment about ADM.
The same filing reported $11.1 billion of total available liquidity as of June 30, 2026, consisting of cash and cash equivalents and unused lines of credit. ADM also stated that it believed cash from operations, cash on hand, and unused credit lines would be sufficient to meet its ongoing liquidity requirements for at least the following 12 months.
The example illustrates an important distinction:
Earnings can rise while operating cash flow falls, but that divergence alone does not establish a liquidity crisis.
The cash-flow decline must therefore be interpreted alongside its cause and the company’s available liquidity.
How to Check a Company’s Cash Position in an SEC Filing
To investigate why profitable companies run out of cash, start with the Statement of Cash Flows for a U.S. public company.
Compare net income with operating cash flow and examine the adjustments that reconcile the two.
Next, use the balance sheet to investigate significant changes in cash, receivables, inventory, accounts payable, short-term borrowings, and current debt.
Then read Management’s Discussion and Analysis (MD&A), especially the discussion of liquidity and capital resources.
The SEC’s MD&A guidance emphasizes analysis of cash requirements, sources of cash, material trends and uncertainties, capital expenditures, and the reasons behind material changes in cash flows.
That makes MD&A particularly useful because the financial statements show what changed, while management’s discussion can provide context for why it changed and what constraints remain.
Profitability, Cash Generation, and Liquidity Are Not the Same
Keep these three concepts separate when analyzing a company:
| Concept | Question to Ask |
|---|---|
| Profitability | Is the company generating accounting earnings? |
| Cash generation | Are operations converting economic activity into cash? |
| Liquidity | Can the company meet obligations when they come due? |
A company can be strong on one measure and weaker on another.
Net income is therefore an important part of financial analysis, but it is not a complete measure of a company’s cash position.
The Bottom Line
Understanding why profitable companies run out of cash requires looking beyond net income.
The key is to determine where the cash went, whether the requirement is temporary or recurring, and whether the company can sustainably fund the gap.
That distinction can reveal financial pressure that positive net income alone may not show.
This article is for educational purposes only and does not constitute personalized investment advice. Financial conditions, accounting considerations, and liquidity risks vary by company and industry.
📚 Related Articles
Free Cash Flow Explained: Why Profitable Companies Can Still Run Into Trouble
Revenue vs Profit: Why Strong Sales Growth Can Mislead Investors
Before You Buy the Dip: 5 Critical Balance Sheet Checks Every Investor Should Make
High Interest Rates and the Economy: Why Can Growth Stay Strong?
If high interest rates are supposed to slow the economy, why can consumers keep spending,…
Can AI Become a Monopoly? Where the Real Economic Moats Are
Artificial intelligence appears to have many ingredients that could produce powerful monopolies. Training frontier models…
Can Big Tech Maintain Its Profit Margins in the AI Era?
Artificial intelligence is creating new revenue opportunities for Big Tech, but it is also changing…