If high interest rates are supposed to slow the economy, why can consumers keep spending, businesses keep investing, and economic growth remain positive?
The apparent contradiction comes from treating the policy rate as if it were the interest rate everyone pays today.
It is not.
A homeowner with a low fixed-rate mortgage, a company with bonds that do not mature for five years, and a business funded with floating-rate loans can all live under the same Federal Reserve policy while experiencing very different financial conditions.
That is the key to understanding high interest rates and the economy: monetary tightening does not reach every borrower at the same time.
When economic data remain resilient despite restrictive rates, the first thing I would check is not whether monetary policy has “failed.” I would check where current market rates are actually entering household and corporate cash flows.
That leads to a more useful concept than a simple recession countdown: the refinancing clock.
The policy rate tells us the price of new money. The refinancing clock helps tell us when that price reaches existing borrowers.
Why High Rates and a Strong Economy Can Coexist
The United States currently provides a useful example.
On September 16, 2026, the Federal Open Market Committee raised the federal funds target range by 25 basis points to 3.75%–4.00%.
Yet the Federal Reserve’s September 2026 FOMC statement described economic activity as expanding at a “solid pace,” with resilient domestic spending, strong productivity growth, and robust capital investment.
The Fed’s September Summary of Economic Projections showed a median projection of 2.3% real GDP growth for 2026, alongside a 4.1% unemployment rate and 3.7% PCE inflation.
Those figures are projections, not guaranteed outcomes. But they illustrate the puzzle: restrictive monetary policy and continued economic growth can exist at the same time.
The reason is not that rates have stopped mattering. Their impact is uneven, delayed, and heavily dependent on existing debt structures and balance sheets.
This uneven transmission is one reason high interest rates and the economy can appear disconnected for longer than investors expect.
High Interest Rates Do Not Hit Everyone at the Same Time
Consider two hypothetical homeowners.
Homeowner A has a $400,000 mortgage carrying a 3.5% fixed rate obtained several years ago.
Homeowner B wants to borrow the same amount today at a substantially higher mortgage rate.
Both households live under the same monetary policy, but they do not experience the same financial conditions.
Homeowner A’s existing principal and interest payment does not automatically increase when market rates rise. Homeowner B feels the higher financing cost at once.
This illustrates an important distinction between the stock of existing debt and the flow of new credit.
Higher rates reach new mortgages, floating-rate borrowing, newly issued corporate debt, and refinanced loans much faster than they reach older fixed-rate obligations.
That helps explain why housing affordability and mortgage activity can weaken while millions of existing homeowners continue making essentially the same scheduled payments.
Monetary policy is affecting economic behavior. It simply is not reaching everyone on the same schedule.
Companies Can Still Be Paying Yesterday’s Interest Rates
The same mechanism applies to businesses.
Imagine two hypothetical companies that each have $1 billion of debt.
Company A issued long-term fixed-rate debt at 3%:
$1 billion × 3% = $30 million in annual interest
Company B must refinance the same amount at 7%:
$1 billion × 7% = $70 million in annual interest
That is an additional $40 million per year.
Today’s policy rate alone cannot tell us how much pressure either company faces. We also need to know whether its debt is fixed or floating, when it matures, how much free cash flow the company generates, and whether it needs additional financing.
The refinancing clock helps make that difference visible.
The Refinancing Clock Framework
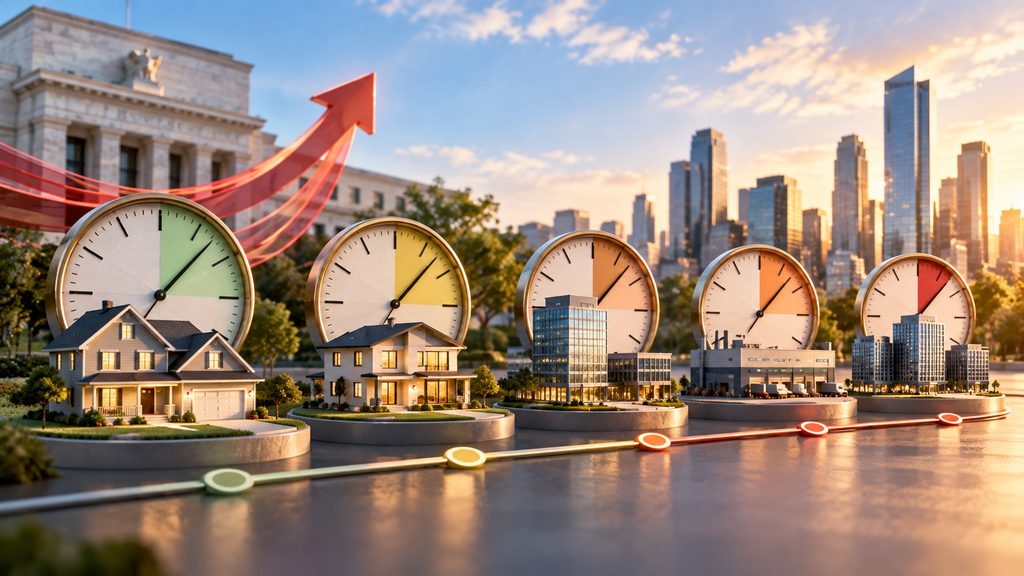
Think of households and companies as carrying thousands of different financial clocks.
One loan resets next month. Another bond matures next year. A fixed-rate mortgage may remain unchanged for many years.
The central bank can change today’s financing environment immediately, but these individual clocks help determine when higher rates actually reach each borrower.
The transmission process can be simplified as:
Higher policy rates → higher borrowing costs → refinancing at higher rates → higher interest expense → pressure on spending and investment
Every borrower moves through that sequence at a different speed.
Instead of asking whether rates are simply “high enough” to hurt the economy, investors can examine four variables:
Rate Exposure → Reset Timing → Financial Buffer → Demand Response
| Borrower | Rate Exposure | Reset Timing | Financial Buffer | Near-Term Pressure |
|---|---|---|---|---|
| Homeowner with low fixed mortgage | Low | Distant | Varies | Limited |
| New homebuyer | High | Immediate | Depends on income | High |
| Cash-rich company with little debt | Low | Limited | Strong | Limited |
| Leveraged company with floating-rate debt | High | Immediate | Weak/moderate | High |
| Company with major debt maturity approaching | Rising | Near-term | Depends on cash flow | Increasing |
The framework asks four questions:
1. Rate Exposure: Who is actually exposed to current market rates?
2. Reset Timing: When will existing debt mature, refinance, or reprice?
3. Financial Buffer: Does the borrower have enough income, cash flow, savings, or liquidity to absorb the higher cost?
4. Demand Response: Is that pressure actually changing consumption, investment, hiring, or other behavior?
These questions explain why one interest-rate environment can produce very different outcomes across the economy.
Aggregate Resilience Can Hide Financial Stress
Headline economic data can hide problems among more rate-sensitive borrowers.
The Federal Reserve’s May 2026 Financial Stability Report assessed vulnerabilities from business and household debt as moderate. Combined business and household debt relative to GDP had declined to levels not seen since the early 2000s, while household balance sheets remained strong overall.
But the aggregate picture was not uniformly positive.
Debt-servicing capacity was weaker among some non-investment-grade public companies and riskier private firms, especially those dependent on floating-rate leveraged loans and private credit. Credit-card and auto-loan delinquencies also remained elevated relative to the past decade.
These findings can coexist because financial starting points differ.
A cash-rich company with modest leverage and distant maturities can absorb higher rates differently from a heavily leveraged borrower that must refinance next year.
Aggregate resilience does not mean universal resilience.
Higher borrowing costs tend to expose weaker balance sheets first.
There is also a smaller offset: higher yields can increase interest income for households holding savings accounts, money-market instruments, Treasury securities, and other interest-bearing assets.
That does not make restrictive monetary policy broadly stimulative. It simply shows that the same rate environment can produce different cash-flow effects across the economy.
This distinction matters when interpreting high interest rates and the economy from headline data alone.
Strong Growth Does Not Mean High Rates Are Doing Nothing
Suppose an economy would have grown 4% under easier financial conditions but grows 2% instead.
The economy is still expanding, yet tighter monetary policy may have reduced growth substantially.
We observe the 2% economy. We cannot directly observe the alternative 4% economy that never occurred.
This is the counterfactual problem.
Higher rates can restrain housing, borrowing, consumption, investment, and asset prices without pushing total economic activity into contraction.
“Still growing” and “unaffected by high rates” are not the same statement.
Other forces can also offset some of the drag. Productivity can improve, real incomes can rise, and profitable companies can continue investing despite higher financing costs. Cash-rich businesses may not need much external financing at all.
The Federal Reserve’s September 2026 statement, for example, highlighted strong productivity growth and robust capital investment while describing economic activity as expanding at a solid pace.
A better mental model is therefore not:
High rates = weak economy
It is closer to:
Economic growth = supportive forces − restrictive forces
The observed economy reflects the combination of both.
There Is No Universal Monetary-Policy Lag
Investors often hear that interest-rate changes affect the economy “with a lag.”
That is broadly true, but there is no universal countdown where a rate change must produce a particular outcome exactly 12, 18, or 24 months later.
The timing depends on the structure of the economy: fixed versus floating debt, corporate maturity schedules, bank lending standards, household balance sheets, internal business financing, and income growth.
Different conditions create different transmission speeds.
Understanding high interest rates and the economy therefore requires more than tracking how many months have passed since the Federal Reserve changed rates.
It is more accurate to think about many overlapping lags than one fixed monetary-policy lag.
Fixed-Rate Debt Delays the Impact. It Does Not Eliminate It.
Consider a hypothetical company with $5 billion of debt carrying a 3% rate.
Annual interest expense:
$5 billion × 3% = $150 million
If that debt eventually has to be refinanced at 6%:
$5 billion × 6% = $300 million
The company now faces an additional $150 million of annual interest expense.
That can reduce cash available for capital expenditures, hiring, acquisitions, dividends, share repurchases, or debt reduction.
Nothing necessarily went wrong with the underlying business. The financing environment simply caught up with it.
The duration of restrictive rates can therefore matter almost as much as the initial increase.
A short period of high rates may leave many fixed-rate borrowers relatively insulated. Keep rates elevated long enough, and more refinancing clocks eventually reach zero.
Four Signals Investors Should Watch
To understand whether high interest rates and the economy are becoming more tightly connected through monetary transmission, investors can monitor four channels.
1. Household Cash Flow
Watch debt-service burdens, credit-card and auto-loan delinquencies, mortgage affordability, real disposable income, and consumer spending.
What matters is whether higher financing costs are beginning to change household behavior.
2. Corporate Refinancing
Watch debt maturity schedules, fixed versus floating rates, interest expense, interest coverage, free cash flow, credit spreads, and refinancing activity.
A company that looks financially comfortable today can become more vulnerable as a large maturity approaches.
3. Credit Availability
Higher benchmark rates are only part of the tightening process.
Stricter lending standards, wider credit spreads, and reduced access to financing can amplify the pressure, particularly for smaller or highly leveraged businesses.
4. Real Demand
Finally, look for changes in actual behavior.
Are households reducing discretionary purchases? Are businesses delaying projects? Is hiring slowing? Are capital expenditures or residential investment weakening?
A cluster such as:
Higher refinancing costs → weaker interest coverage → reduced capital spending → slower hiring → weaker household income growth → softer consumption
would suggest monetary restraint is moving beyond financial markets and deeper into the real economy.
The opposite evidence matters too. Strong productivity, healthy income growth, resilient balance sheets, and internally financed investment can help the economy absorb elevated rates for longer.
Final Takeaway
A resilient economy does not prove that high interest rates have stopped working.
It may mean that monetary tightening is still moving through the system unevenly.
For investors, the Refinancing Clock Framework provides a more useful way to interpret high interest rates and the economy:
Rate Exposure → Reset Timing → Financial Buffer → Demand Response
The policy rate tells us the price of new money.
The refinancing clock helps tell us when that price reaches existing borrowers.
And Demand Response helps reveal when financial pressure is beginning to change the trajectory of the real economy.
FAQ
Q1. Why does refinancing matter so much when interest rates stay high?
Existing fixed-rate debt can temporarily protect households and companies from higher market rates. As that debt matures or is replaced, refinancing can increase interest expense and leave less cash available for consumption, investment, hiring, or other uses.
Q2. What should investors watch when interest rates remain high?
Watch household cash flow, corporate refinancing, credit availability, and real demand rather than focusing only on the federal funds rate. Together, these channels provide better evidence of whether monetary tightening is spreading through the economy.
This article is for educational purposes only and does not constitute personalized investment advice.
📚 Related Articles
Interest Rates and the Stock Market: A Beginner’s Practical Guide
Recession Signals: 6 Key Indicators Investors Should Watch
Inverted Yield Curve: A Critical Guide to Avoid Costly Recession Mistakes
Can AI Become a Monopoly? Where the Real Economic Moats Are
Artificial intelligence appears to have many ingredients that could produce powerful monopolies. Training frontier models…
Can Big Tech Maintain Its Profit Margins in the AI Era?
Artificial intelligence is creating new revenue opportunities for Big Tech, but it is also changing…
Free Cash Flow vs Earnings: Why Profits Can Rise While Cash Flow Falls
A company reports higher earnings. Revenue is growing, margins look healthy, and net income reaches…