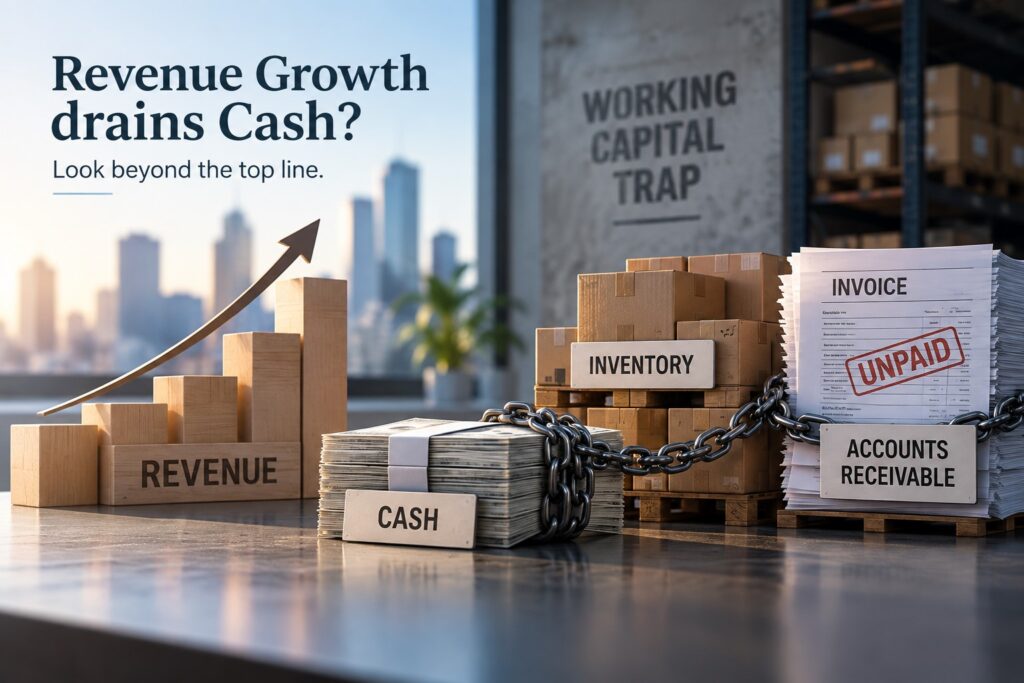
A company reports 30% revenue growth. Net income is rising. Demand appears strong.
Yet operating cash flow is falling.
That combination may look contradictory, but it can happen when growth requires a business to put increasing amounts of cash into receivables and inventory before that cash returns. This is the working capital trap investors can miss when they focus on the income statement alone.
Growing companies often need more working capital, so an increase is not automatically a warning sign. The more useful question is:
How much additional cash does the business have to commit for each additional dollar of revenue?
That question turns working capital from an accounting definition into a practical way to examine the cash intensity and quality of growth.
Why Revenue Growth Can Consume Cash
Revenue and cash collection do not necessarily occur at the same time.
A company may purchase materials, build inventory, sell a product on credit, recognize revenue, and then wait weeks or months for the customer to pay.
The operating cycle can therefore look like this:
Cash spent → inventory → sale → receivable → cash collected
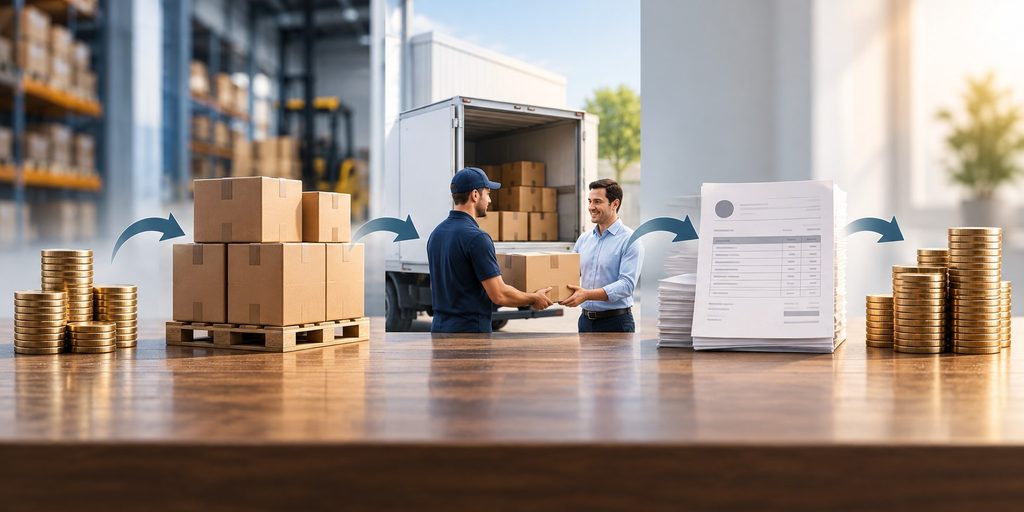
Rapid growth can increase the amount of money moving through that cycle.
Three balance-sheet accounts are especially useful:
- Accounts receivable (AR): amounts customers owe the company.
- Inventory: goods and materials that have not yet been sold.
- Accounts payable (AP): amounts the company owes suppliers.
An increase in receivables or inventory generally absorbs cash, all else equal. An increase in payables can partially offset that pressure because the company has not yet paid those additional supplier obligations.
This is one reason higher accounting profit does not necessarily produce an equivalent increase in operating cash flow.
Case Study: Northstar Components Grows 30%
Consider a hypothetical manufacturer called Northstar Components.
All figures in this case study are fictional and are used only to demonstrate the analytical method.
| Year 1 | Year 2 | Change | |
|---|---|---|---|
| Revenue | $100M | $130M | +$30M |
| Accounts Receivable | $15M | $27M | +$12M |
| Inventory | $10M | $18M | +$8M |
| Accounts Payable | $8M | $10M | +$2M |
The headline looks strong.
Revenue increased from $100 million to $130 million, or 30%.
But follow the cash.
Receivables increased by $12 million, while inventory increased by another $8 million. Together, those accounts absorbed $20 million.
Accounts payable increased by $2 million, providing a partial offset.
For this simplified example:
Additional operating working capital = $12M + $8M − $2M = $18M
Northstar produced $30 million of additional revenue while $18 million of additional cash became tied up in these three operating accounts.
That does not mean Northstar lost $18 million. It means its growth came with a substantial cash requirement.
The working capital trap becomes easier to see when revenue growth is compared with the cash required to support it.
Measuring the Working Capital Trap
We can turn the Northstar example into a diagnostic calculation.
Simplified Incremental Working Capital Ratio
= (Δ Accounts Receivable + Δ Inventory − Δ Accounts Payable) ÷ Δ Revenue
For Northstar:
= ($12M + $8M − $2M) ÷ $30M
= 60%
In this simplified case, approximately $0.60 became tied up in these working-capital accounts for every $1 of additional revenue.
Northstar’s sales are growing, but those additional sales require a significant commitment of cash before the operating cycle converts them back into cash.
The next question is why.
Customers may be paying more slowly. Northstar may be deliberately building inventory ahead of stronger demand. Sales may have accelerated late in the reporting period. Supplier terms may have changed.
The calculation identifies the pressure point. The underlying cause still has to be tested.
Important: This Is a Diagnostic Tool, Not a Standard Ratio
The simplified incremental working-capital ratio used here is not a standardized accounting or valuation ratio.
There is no universal level at which it automatically becomes good or bad.
Retailers, manufacturers, distributors, software businesses, and construction companies can have fundamentally different inventory requirements, customer payment terms, supplier relationships, and seasonal patterns.
The calculation is therefore most useful when examining changes within the same business over time, or when comparing businesses with sufficiently similar operating models.
Its purpose is diagnostic:
Is growth becoming more or less cash-intensive, and what changed?
Same Revenue Growth, Very Different Cash Requirements
Consider two hypothetical companies that each generate $30 million of additional revenue.
| Company A | Company B | |
|---|---|---|
| Additional Revenue | $30M | $30M |
| Increase in Accounts Receivable | $7M | $12M |
| Increase in Inventory | $5M | $8M |
| Increase in Accounts Payable | $4M | $2M |
| Simplified Additional Working Capital | $8M | $18M |
| Cash Tied Up per $1 of Revenue Growth | $0.27 | $0.60 |
A revenue-growth screen might make the two companies look identical.
Their cash requirements are not.
Company A commits about $0.27 to these working-capital accounts for every additional dollar of revenue. Company B commits $0.60.
Instead of asking only which company is growing faster, ask:
Why does one business require more than twice as much incremental working capital to produce the same additional revenue?
Possible explanations include customer payment terms, inventory requirements, supplier bargaining power, product mix, seasonality, or operating efficiency.
Company B could also be deliberately preparing for stronger future demand. The difference is therefore a reason to examine the operating cycle, not a mechanical verdict on business quality.
Step 1: Are Receivables Growing Faster Than Revenue?
Northstar’s revenue increased 30%.
Accounts receivable increased from $15 million to $27 million:
Receivables growth = 80%
That gap deserves a second check.
But there is an important distinction:
Receivables growing faster than revenue does not prove that customers are paying more slowly.
A balance sheet is a snapshot. Seasonality, customer mix, payment terms, acquisitions, or unusually strong sales near the reporting date can affect the ending receivables balance.
A useful follow-up measure is Days Sales Outstanding (DSO).
A simplified version is:
DSO = Average Accounts Receivable ÷ Revenue × Number of Days
DSO estimates how long receivables remain outstanding relative to sales. Public-company filings commonly use DSO alongside other working-capital measures to evaluate collection and cash-management efficiency.
If receivables rise because the entire business became larger while DSO remains broadly stable, the increase may be relatively benign.
If DSO persistently rises, collection efficiency may be deteriorating or customer payment terms may have changed.
Higher receivables tell you where to look. A sustained deterioration in collection efficiency provides stronger evidence about what may be changing.
Investor Check: If management attributes higher receivables to quarter-end timing or a temporary customer-payment issue, treat that explanation as something to test. In subsequent reports, check whether DSO normalizes, receivables convert into cash, and operating cash flow recovers.
Step 2: Is Inventory Supporting Growth or Hiding a Demand Problem?
Northstar’s inventory increased from $10 million to $18 million—an 80% increase against 30% revenue growth.
Inventory growth can reflect preparation for stronger demand, additional safety stock, or a new product launch. It can also signal slower-than-expected sales.
The distinction becomes clearer when inventory growth is compared with turnover and subsequent sales.
If inventory rises sharply while inventory turnover deteriorates, the combination requires closer attention. A temporary build followed by stronger sales and normalization tells a different story from inventory that repeatedly grows faster than sales and becomes increasingly difficult to move.
The useful question is not simply whether inventory increased, but:
Did the company’s ability to convert inventory into sales change?
Step 3: Is Accounts Payable Making Cash Flow Look Better?
Working capital can affect interpretation in the opposite direction.
Suppose a company takes longer to pay suppliers.
Accounts payable rises, allowing the company to retain cash for longer.
Imagine that accounts payable increases from $10 million to $25 million without a comparable increase in purchasing activity.
Operating cash flow could look stronger because an additional $15 million remains unpaid.
The business may have negotiated better supplier terms, or payment timing may simply have changed. Either way, the stronger cash-flow number needs context.
Ask:
Did cash generation improve because the economics of the business improved, or because the timing of payments changed?
This is why working-capital analysis should consider receivables, inventory, and payables together rather than treating any one balance in isolation. Real company filings often track these measures together because changes in each component can affect operating cash flow.
Step 4: Compare Earnings Growth With Cash Conversion
Now add another layer to Northstar.
| Year 1 | Year 2 | |
|---|---|---|
| Net Income | $8M | $12M |
| Operating Cash Flow | $9M | $5M |
Net income increased 50%.
Operating cash flow fell by roughly 44%.
A tempting conclusion would be:
“The earnings are not real.”
That goes too far.
A better analytical sequence is:
Earnings increased → cash conversion weakened → working capital absorbed cash → determine whether the effect is temporary or structural
Suppose Northstar built inventory for a product launch and then collects its receivables normally over the next two quarters. Operating cash flow may recover.
Now consider the opposite case.
Receivables continue to outgrow sales. DSO rises. Inventory efficiency deteriorates. The company needs additional borrowing to finance its operating cycle.
A persistent gap between earnings growth and cash conversion can be an important sign of a developing working capital trap.
The initial numbers may look similar in both situations. Subsequent financial statements determine which interpretation fits the evidence.
The Working Capital Trap Can Also Reverse
Working capital can release cash as well as absorb it.
Suppose Northstar’s growth slows next year.
Customers pay old invoices, reducing receivables. The company sells existing inventory but does not replenish it at the same pace.
Cash is released from working capital.
Operating cash flow may suddenly look excellent even though the underlying business is growing more slowly.
This creates an important symmetry:
Rapid growth can temporarily make cash flow look weaker than the business.
Slower growth can temporarily make cash flow look stronger than the business.
That is why the source of cash generation matters as much as the headline operating cash-flow number.
Healthy Growth vs. a Working Capital Trap
The difference becomes clearer when we compare two patterns.
Scenario A: Cash-Intensive but Healthy Expansion
Revenue grows 25%.
Receivables broadly track sales. Inventory increases because management is supporting higher demand, while inventory efficiency remains relatively stable.
Operating cash flow is temporarily pressured but later improves as customers pay and inventory converts into sales.
The company may simply be financing expansion.
Scenario B: Deteriorating Cash Conversion
Revenue grows 10%.
Receivables grow 35%. Inventory grows 45%.
DSO increases, inventory efficiency deteriorates, and operating cash flow repeatedly falls behind earnings.
The company increasingly relies on borrowing or other financing to support the operating cycle.
Here, working capital is not merely expanding with the business. It is consuming progressively more cash relative to the growth being produced.
The risk becomes more serious when deteriorating cash conversion is combined with limited liquidity or rising dependence on external financing. In that situation, growth itself can increase financial pressure.
A Practical Revenue Growth Quality Test
To determine whether strong growth is creating a working capital trap, work through the financial statements in this sequence.
1. Measure incremental revenue.
How many additional dollars of sales did the company generate?
2. Estimate the incremental working-capital requirement.
How much additional cash became tied up in receivables and inventory after considering relevant operating liabilities such as payables?
3. Compare the two.
How much incremental working capital was required for each incremental dollar of revenue?
4. Find the account driving the change.
Was the pressure concentrated in receivables, inventory, payables, or several accounts?
5. Test operating efficiency.
Where appropriate, examine DSO and inventory turnover rather than relying only on ending balances.
6. Compare earnings with operating cash flow across multiple periods.
One quarter can be noisy. Persistent divergence provides more useful evidence.
7. Read management’s explanation.
Look for seasonality, acquisitions, customer mix, product launches, supply-chain changes, or deliberate inventory investment.
8. Verify the explanation later.
Did receivables actually get collected? Did inventory convert into sales? Did operating cash flow recover?
The final step is particularly important.
Management commentary can provide useful context, but subsequent financial statements allow investors to test whether the explanation was consistent with what actually happened.
That turns financial-statement analysis from a one-quarter snapshot into an evidence-based process.
Conclusion: Growth Has a Cash Price
A working capital trap cannot be identified simply because receivables or inventory increased. What matters is how the company’s cash requirement changes as it grows.
Revenue growth tells us how much a business expanded.
Working capital tells us how much cash that expansion demanded.
The more useful question is:
Is each additional dollar of growth requiring more or less cash than before?
When that cash requirement keeps rising without a convincing operating explanation, strong revenue growth may be hiding a working capital trap.
This article is for educational purposes only and does not constitute personalized investment advice.
📚 Related Articles
Revenue vs Profit: Why Strong Sales Growth Can Mislead Investors
Free Cash Flow Explained: Why Profitable Companies Can Still Run Into Trouble
Why Profitable Companies Run Out of Cash: 5 Causes Investors Should Know
High Interest Rates and the Economy: Why Can Growth Stay Strong?
If high interest rates are supposed to slow the economy, why can consumers keep spending,…
Can AI Become a Monopoly? Where the Real Economic Moats Are
Artificial intelligence appears to have many ingredients that could produce powerful monopolies. Training frontier models…
Can Big Tech Maintain Its Profit Margins in the AI Era?
Artificial intelligence is creating new revenue opportunities for Big Tech, but it is also changing…